Project IRR and NPV
9.0% real pre-tax IRR on ITK capital, 12.6% at Fortescue’s US$6.2bn.
All slides · Open in the deck · Change log
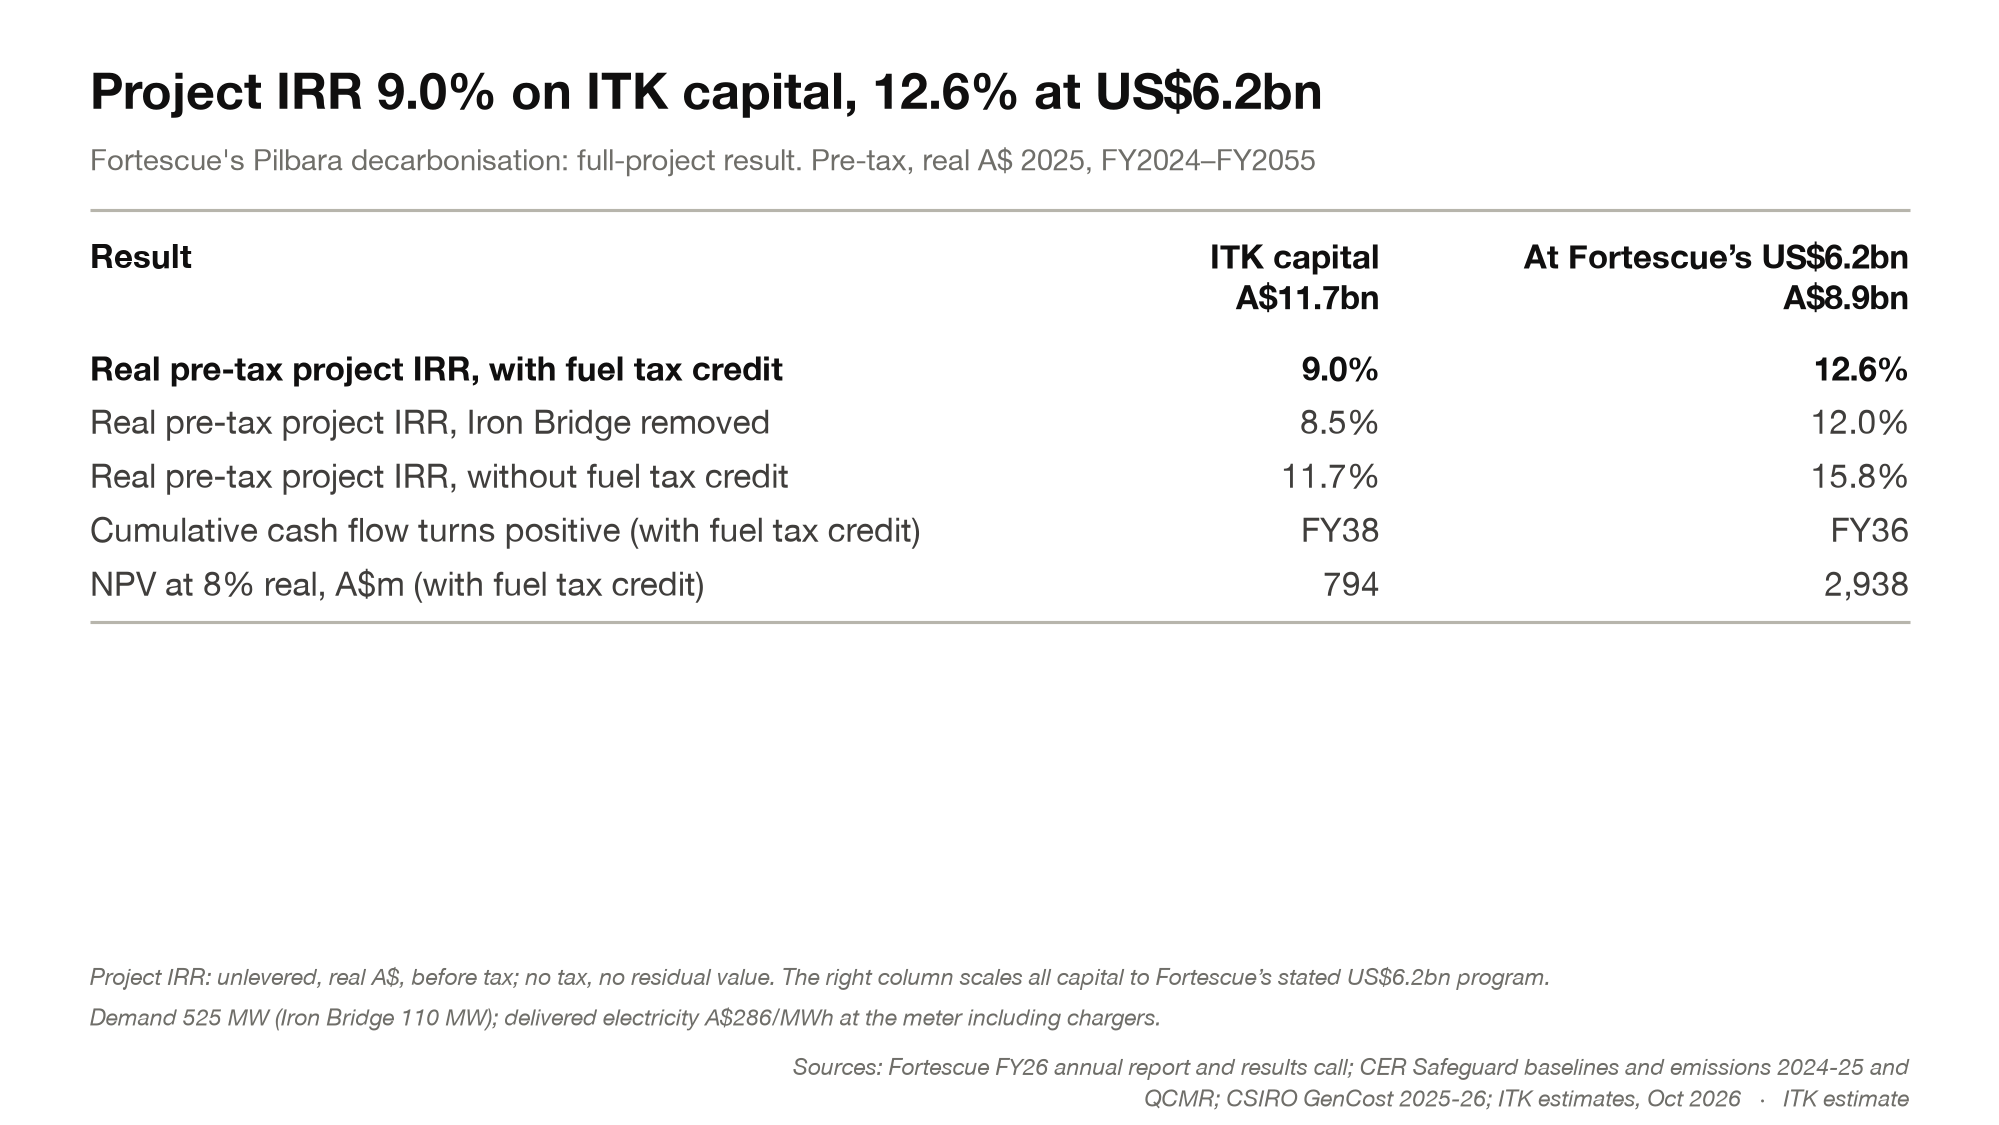
The IRR is the discount rate at which the project’s cash flows, FY24 to FY55, have zero present value: capital and replacements out, annual benefit in. It is real, pre-tax and unlevered, with no residual value.
- With Iron Bridge’s 110 MW load removed, the IRR falls to 8.5% (12.0%).
- Without the fuel tax credit, the diesel saved is worth A$2.50/L instead of A$1.96/L, and the IRR rises to 11.7% (15.8%).
- NPV is at an 8% real pre-tax WACC. At gearing of about 4% (the average of BHP, Rio Tinto and Fortescue), 8% real implies a pre-tax nominal return on equity of about 11%.
The right-hand column scales all capital to Fortescue’s stated US$6.2bn programme.
Sources: Fortescue FY26 annual report and results call; ITK estimates.